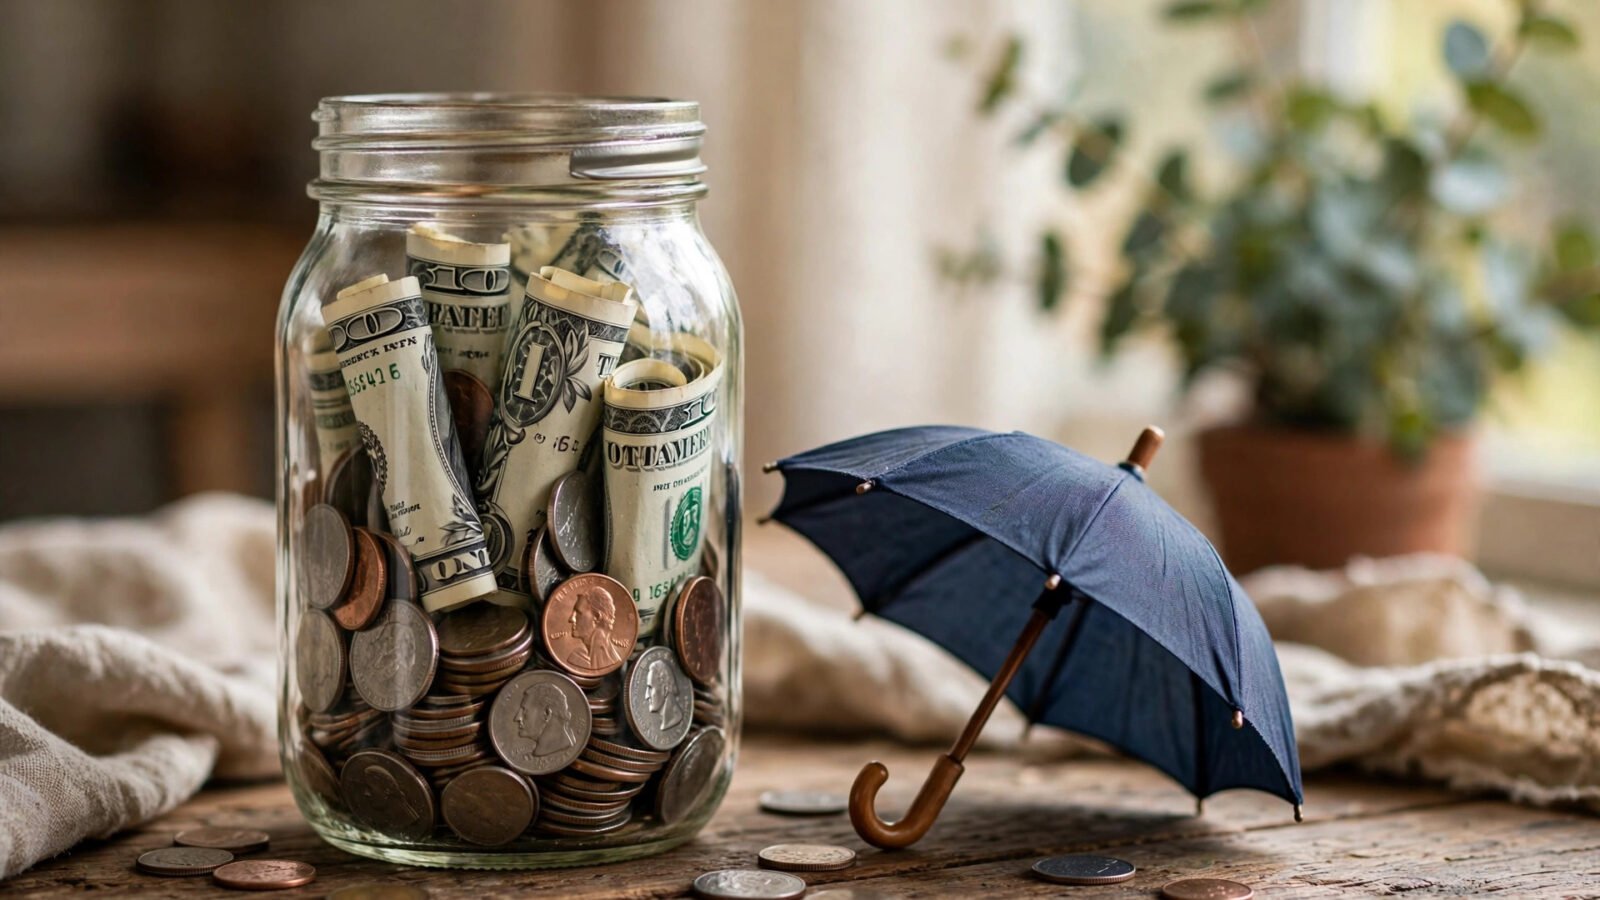
The old rule was three to six months of expenses. The new reality is bigger. Across America, emergency funds are trending bigger this year — savers are targeting six to twelve months of essential costs, and financial planners report clients arriving at meetings already convinced that the old guidance was too thin. They have a point. Between economic uncertainty, the rising cost of everything, and a job market where hiring moves slowly, the price of being unprepared has gone up. The emergency fund is having its moment as the most underrated account in personal finance.
This is not paranoia; it is pattern recognition. The households that weathered recent economic turbulence best were not necessarily the highest earners — they were the ones with cash buffers that bought time and options. Here is why emergency funds are getting bigger, how big yours should actually be, and how to build one without derailing the rest of your financial life.
Why the old 3-to-6-month rule is under pressure
The classic guidance assumed emergencies were brief and re-employment was quick. Both assumptions look shakier now. Job searches take longer in a low-hiring environment — white-collar searches stretching six months or more are common, and severance rarely covers the gap. Meanwhile, the emergencies themselves got more expensive: a single ER visit, a transmission replacement, or a month of COBRA premiums can vaporize a thin fund. When the FDIC’s deposit insurance protects your savings up to $250,000 per bank, there is no safety excuse for keeping the fund small — the constraint is purely behavioral.
There is also a psychological dimension planners keep citing: clients with larger buffers make better decisions everywhere else. They do not panic-sell investments during volatility, do not take predatory loans, and can afford to wait for the right job rather than grabbing the first offer. An emergency fund is not just money; it is negotiating leverage with life. That leverage is worth paying for, which is why the trend toward bigger funds reflects wisdom, not fear.
Who needs the bigger end of the range
Twelve months is not for everyone, but it is right for more people than admit it. Single-income households, freelancers and gig workers with volatile earnings, workers in cyclical industries, the self-employed, and anyone with health conditions or dependents should target the higher end. Dual-income households with stable jobs and strong safety nets can reasonably hold less. The right size is a function of your personal volatility — income stability, job replaceability, health, and dependents — not a universal number. Be honest about yours.
Where to keep it: the hierarchy of emergency cash
Tier one — one month of expenses — belongs in checking or an instantly accessible savings account: this is the “call the plumber at midnight” money. Tiers two and three — the remaining five to eleven months — belong in a competitive high-yield savings account, earning real yield while staying liquid and FDIC-insured. That is the entire structure most people need. Anything more complex — laddered CDs, money market funds, Roth IRA contributions as a backstop layer — is optimization for enthusiasts, not requirement.
What does not belong in an emergency fund: stocks (too volatile — emergencies correlate with market crashes), crypto (same, amplified), CDs with steep early-withdrawal penalties as the primary layer, and — critically — credit cards. A credit line is not an emergency fund; it is an emergency loan at 20-plus percent. The fund’s job is to prevent debt, not to be debt. Building it is mostly a matter of the best habits for saving money every month applied with a single-minded target: automate a transfer the day after payday and treat it as non-negotiable as rent.
Building a bigger fund without pain
The standard advice — “save $1,000, then one month, then three” — still works, but the bigger targets demand better tactics. Windfall capture is the fastest accelerator: tax refunds, bonuses, cash gifts, and side-income should flow to the emergency fund by default until it hits target. Most people treat windfalls as fun money; redirecting even half of them builds a twelve-month fund in a couple of years without touching the monthly budget.
Expense-side funding works too. A temporary “spending freeze” on discretionary categories for 60 to 90 days — funded by making grocery shopping faster and cheaper, pausing subscriptions, and cooking at home — can add thousands quickly. Selling unused items converts clutter to cushion. And employer programs help more than people realize: some companies now offer emergency-savings accounts with auto-enrollment and even matching contributions, a benefit worth asking HR about. The CFPB’s savings resources include worksheets for sizing and building emergency funds step by step.
When the fund is “done” — and what then
A finished emergency fund is a milestone that should trigger a deliberate redirect, not lifestyle inflation. Once you hit your target number, point that automatic transfer at its next mission: maxing retirement accounts, funding a house down payment, or attacking remaining debt. Keep the fund itself boring — parked in high yield, reviewed annually, replenished immediately after any withdrawal. The biggest post-completion mistake is raiding it for non-emergencies; define “emergency” in writing (job loss, medical crisis, essential home/car repair) and enforce it like a contract with yourself.
Revisit the target annually or after life changes — a new child, a mortgage, a career switch all reset the math. And resist the temptation to invest the fund “since emergencies are rare.” Rare is not never, and the fund’s value is measured in the crises it absorbs, not the yield it earns. A bigger emergency fund earning 4 percent that saves you from a 24 percent payday loan is the best investment you will ever make. NerdWallet’s emergency fund guides offer calculators for sizing yours to your actual expenses.
The quiet wealth signal
Here is what the trend toward bigger emergency funds really signals: Americans are learning that financial resilience beats financial optimization. The perfect asset allocation means nothing if a $5,000 emergency forces you to liquidate it at the worst moment. Cash gets mocked as “drag” in bull markets and worshipped in crises — the wise hold it through both.
Emergency funds are trending bigger this year because lived experience keeps teaching the same lesson: the future is lumpy, jobs are fickle, and the only bailout you can count on is the one you built yourself. Build it bigger than comfortable. You will never regret the months of expenses sitting quietly in high yield — but you might deeply regret the months that were not there.
Frequently Asked Questions
How big should my emergency fund be?
The traditional guidance is 3 to 6 months of essential expenses, but many planners now recommend 6 to 12 months depending on your situation. Single-income households, freelancers, and workers in volatile industries should target the higher end; stable dual-income households can hold less.
Where should I keep my emergency fund?
Keep one month in checking for instant access and the rest in an FDIC-insured high-yield savings account. Avoid stocks, crypto, or anything volatile — emergency funds must be stable and liquid precisely when markets are crashing.
Should I pay off debt or build an emergency fund first?
Do both in sequence: build a starter fund of $1,000 to $2,000 first, then attack high-interest debt aggressively, then expand the fund to its full target. Going all-in on debt with zero buffer risks new debt the moment an emergency hits.
Can I use a Roth IRA as an emergency fund?
Roth IRA contributions can be withdrawn anytime tax- and penalty-free, so some use it as a backstop layer — but it should supplement, not replace, a dedicated cash emergency fund. Invested Roth assets can drop exactly when you need them most.
How fast can I build a bigger emergency fund?
Redirect windfalls (refunds, bonuses) by default, automate a payday transfer, and run a temporary 60-to-90-day spending trim. Most households can add several months of expenses within a year without major lifestyle sacrifice.